
ICA in Finance: Beyond PCA for Discovering Hidden Market Factors
Applying Independent Component Analysis to Factor Model in Finance
This paper introduces a novel application of Independent Component Analysis (ICA) to construct Factor Models in finance. By treating stock returns as mixtures of hidden signals, the authors successfully recover independent factors and their corresponding risk sensitivities (betas) for the Arbitrage Pricing Theory (APT) framework.
TL;DR
Factor models are the bedrock of modern finance, yet identifying the "hidden" factors that drive asset returns remains a significant challenge. This paper proposes using Independent Component Analysis (ICA) rather than the traditional Principal Component Analysis (PCA) to extract these factors. By moving beyond simple correlation and leveraging higher-order statistics, ICA reveals the true, independent drivers of market movements.
Background: The Limits of Orthogonality
Financial theories like Arbitrage Pricing Theory (APT) assume that security returns are generated by a set of underlying factors () and sensitivities (). Historically, researchers have used PCA to find these factors. However, PCA has two fatal flaws in a financial context:
- Orthogonality Constraint: PCA assumes factors must be perpendicular (orthogonal) to each other, which isn't necessarily true in real-world economics.
- Gaussian Bias: PCA only uses second-order statistics (mean and variance), ignoring the "fat tails" and complex distributions typical of market data.
Methodology: ICA as Blind Source Separation
The authors re-imagine the stock market as a "cocktail party" where multiple speakers (hidden factors) are talking at once, and we only hear the combined noise (stock returns). ICA is used to "unmix" these signals.
The Mathematical Mapping
The standard multi-factor model is expressed as:
The authors transform this into the ICA framework:
- Mixing Matrix (): Represents the factor sensitivities ().
- Source Signals (): Represents the hidden independent factors ().
- Observations (): The zero-meaned return series of the stocks.
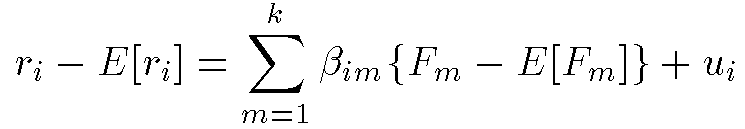
The Workflow
- Preprocessing: Calculate returns from price series and subtract the mean (centering).
- Separation: Run the ICA algorithm to find the demixing matrix .
- Ranking: Sort the separated signals by their norm to identify the most significant factors.
- Reconstruction: Use the mixing matrix (the inverse of ) to retrieve the coefficients.
Experiments: Decoding the Hang Seng Index
The researchers tested this on 7 major stocks from the Hang Seng Index. By applying ICA, they were able to derive a full mixing matrix where each entry represents a stock's sensitivity to a specific independent factor.
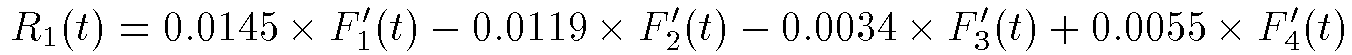
In their 7-factor model, they treated the 7th factor () as the residual (), successfully isolating the idiosyncratic noise from the systematic drivers. This allowed for a cleaner reconstruction of the return generating process than traditional methods.
Critical Analysis & Future Outlook
Takeaway
The shift from PCA to ICA in finance is a shift from correlation to independence. ICA provides a more granular and mathematically rigorous way to define "factors," which is essential for constructing portfolios that are truly hedged against specific market risks.
Limitations
- Stationarity: The model assumes the mixing matrix (sensitivities) is constant over time, which may not hold during periods of extreme market volatility or structural breaks.
- Interpretation: While ICA finds mathematically independent factors, assigning economic names (e.g., "Interest Rate Factor" or "Oil Price Factor") to these hidden signals remains an empirical challenge.
Future Work
Future research could explore Non-linear ICA or Kernel ICA to capture even more complex dependencies in global markets, potentially integrating these hidden factors into automated trading systems.
Main Contribution: This work bridges the gap between signal processing (ICA) and financial econometrics, providing a superior alternative to PCA for factor discovery in the APT framework.